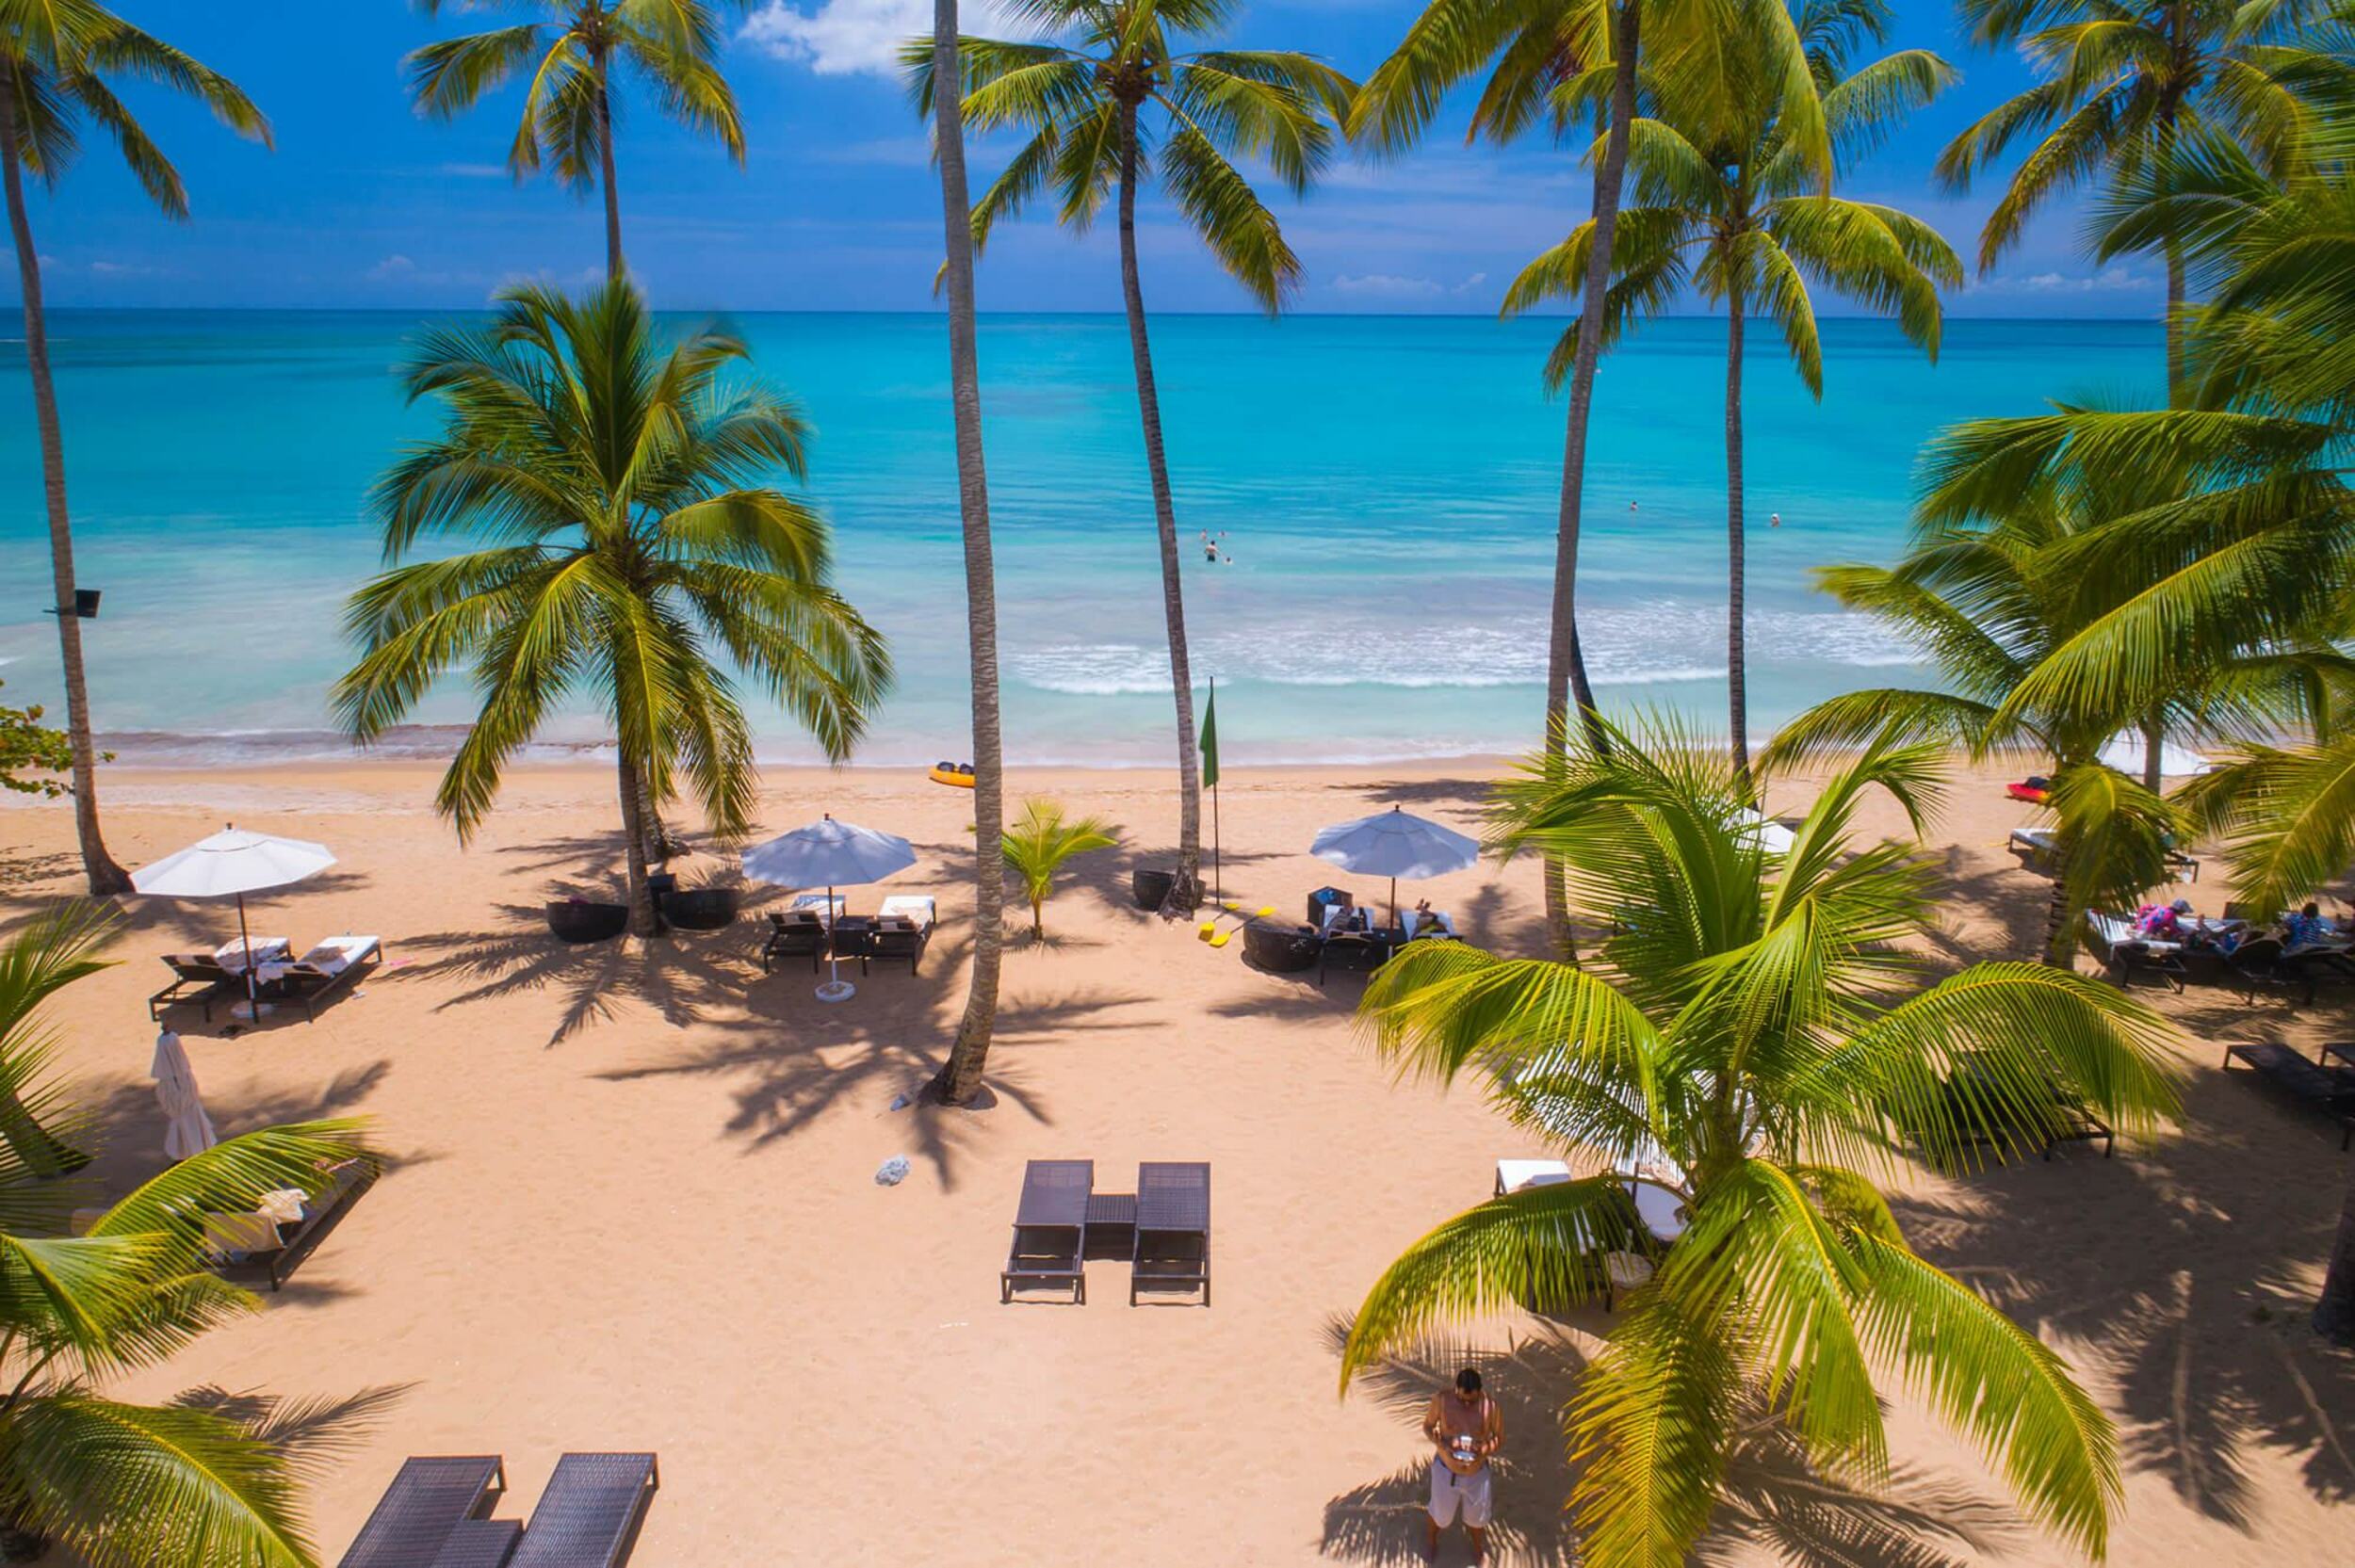
In terms of public policy for the tourism sector, the Dominican Republic has remained consistent with its growth objectives since the 1970s. The country’s attributes as a destination for visitors have been leveraged to achieve sustained and uninterrupted growth, which has resulted in the creation of more hotel rooms and improved hotel and tourism infrastructure. However, it was only during the last 15 years, following the enactment of Law No. 158-01 on the Promotion of Tourism Development, that the country’s tourism offering began to diversify, adding to the “all-inclusive” concept, which made the country internationally recognized, different tourism facilities such as golf courses, theme parks, aquariums, convention centers, and tourism real estate developments such as villas and tourist apartments, among others.
At the beginning of the 1980s, the country had only five thousand hotel rooms; by the end of 2014, that supply had reached nearly seventy thousand rooms. From the three hundred eighty-three thousand tourists arriving in 1980, today the number of arrivals exceeds five million visitors. It should also be noted that the last decade has witnessed significant growth in domestic tourism.
These extraordinary results in the evolution of an economic sector have not been the result of chance. The political decision to achieve such growth was accompanied by an adequate legal framework tailored to the sector’s diverse needs.
Indeed, this framework accurately reflected the governmental decisions adopted in pursuit of such growth. Accordingly, the country went through different periods that, to a greater or lesser extent, corresponded with the interests and priorities of each moment. Taking this into consideration, the legal evolution of the tourism sector may be characterized by the differentiation of the following periods:
1) Initial Tourism Development Stage – from 1971 to the mid-1980s: This stage was characterized by the need to establish an appropriate framework for the creation of hotel infrastructure. For this purpose, Law No. 153-71 was enacted, granting significant tax exemptions for new tourism projects. The promotion of an original and accessible hotel offering undoubtedly contributed to achieving an enviable position within the international tourism market. The Dominican Republic thus began its path toward becoming one of the leading tourism destinations among Latin American countries.
2) Consolidation Stage – from the mid-1980s to 2001: Tax benefits and tourism incentives proved effective. This period reflects an extraordinary increase in the construction of new hotels in the country, primarily in the tourism areas of Puerto Plata–Playa Dorada and Punta Cana. The country grew from having eight thousand rooms to more than fifty thousand. Tourist arrivals also increased significantly, from nearly seven hundred thousand in 1985 to three million visitors in 2000, according to sources from the Central Bank of the Dominican Republic.
3) Diversification Stage of Complementary Tourism Facilities – from 2001 onward: It may be stated that, with the maturity and creation of internationally significant tourism destinations such as Puerto Plata and Punta Cana, driven by the diverse hotel offering under the all-inclusive concept, it became necessary in 2001 to establish an appropriate framework that would encourage not only the creation of hotels in undeveloped tourism areas, but also the development of complementary tourism facilities throughout the national territory.
Tourists arriving at hotels required additional tourism offerings beyond enjoying sun and beaches. It became necessary to provide incentives for the creation of golf courses, theme parks, restaurants, among other facilities, in order to diversify the tourism offering.
The legislator’s task was to approve an essential legislative instrument that included tax exemptions for the creation of such facilities, which —although contemplated in its predecessor, Law No. 153-71— had not developed as expected. With the enactment in 2001 of Law No. 158-01 on the Promotion of Tourism Development, the purpose was to promote the development of tourism infrastructure in areas where such development had not yet begun, and to ensure the creation of additional tourism facilities that would complement the existing hotel offering in destinations that had already reached an advanced level of development and maturity. The tax exemptions provided were highly generous, including income tax exemptions for classified projects for a period of 10 years, as well as exemptions from real estate transfer taxes and import taxes for initial equipment.
One year after this legal framework entered into force, it was also necessary to include a type of tourism accommodation offering that had not initially been contemplated, in order to complement the creation of these new facilities. Accordingly, Law No. 184-02 established that tourism accommodations in general, such as villas and apartments constructed to support complementary tourism facilities —for example, golf courses— would also benefit from the same tax exemptions.
Thus began sustained growth in the tourism real estate sector, which continues to this day as support for the creation of new tourism infrastructure. This new offering diversified accommodation options available in the country, later creating opportunities for the development of condo-hotels and other new forms of tourism lodging.
The major process of consolidating the country as a world-class tourism destination has led the Dominican Republic to establish new objectives, including achieving ten million tourists in the coming years.
To accomplish this goal, among other actions, Law No. 195-13 was approved, modifying Law No. 158-01 on the Promotion of Tourism Development and extending the tax exemption period established under the legislation from 10 to 15 years.
In this way, the evolution of the legal framework for tourism sector investment incentives concludes with a series of benefits —most of which have been in force since 2001, but now with an extended 15-year exemption period— applicable to investments in hotels, complementary tourism facilities, and tourism real estate developments, among which the following stand out:
- Tax exemptions for a period of 15 years for new projects and previously classified projects: this period also applies to tourism projects previously approved whose tax exemptions are currently being used.
- 100% income tax exemption: applicable for a period of 15 years of project operation.
- 100% exemption from value-added tax (ITBIS) and import taxes: applicable to all materials, furniture, and equipment required for the construction and initial outfitting of the project.
- 100% exemption from real estate transfer tax.
- Exemptions for existing hotels: existing hotels that are more than 15 years old may obtain all tax exemptions provided under the law, provided they demonstrate that their remodeling or reconstruction represents more than 50% of the original investment. If the renovation is partial and does not reach such percentage, they will receive a 100% tax exemption for equipment and goods used in the renovation, whether purchased domestically or imported.
- Exemption for operating or management companies: companies managing approved tourism projects that require classification must submit all requirements for consideration. The exemption period will be limited to the terms established in the operating agreements executed with developers, which may not exceed the period granted by law.**
In summary, the current legal framework regarding incentives for tourism investment in the Dominican Republic is the result of a carefully planned, structured, and sustained evolution over time. The diverse tourism offering —hotels, golf courses, tourist villas and apartments, aquariums, theme parks, themed hotels, and restaurants, among others— is precisely the result of the combined efforts of both the public and private sectors —national and international— to create facilities capable of receiving an increasing number of tourists in the country. However, such efforts would not have been possible without the investment tax benefits established in legislation over the past four decades.
For new investors, both in hotels and complementary tourism offerings, the investment tax incentive regime is one of the most attractive in the region. It remains to be evaluated at the end of the coming five-year period what results will be achieved regarding the country’s new objectives: precisely, reaching the arrival of 10 million tourists to the Dominican Republic and having the necessary infrastructure to accommodate them.
